
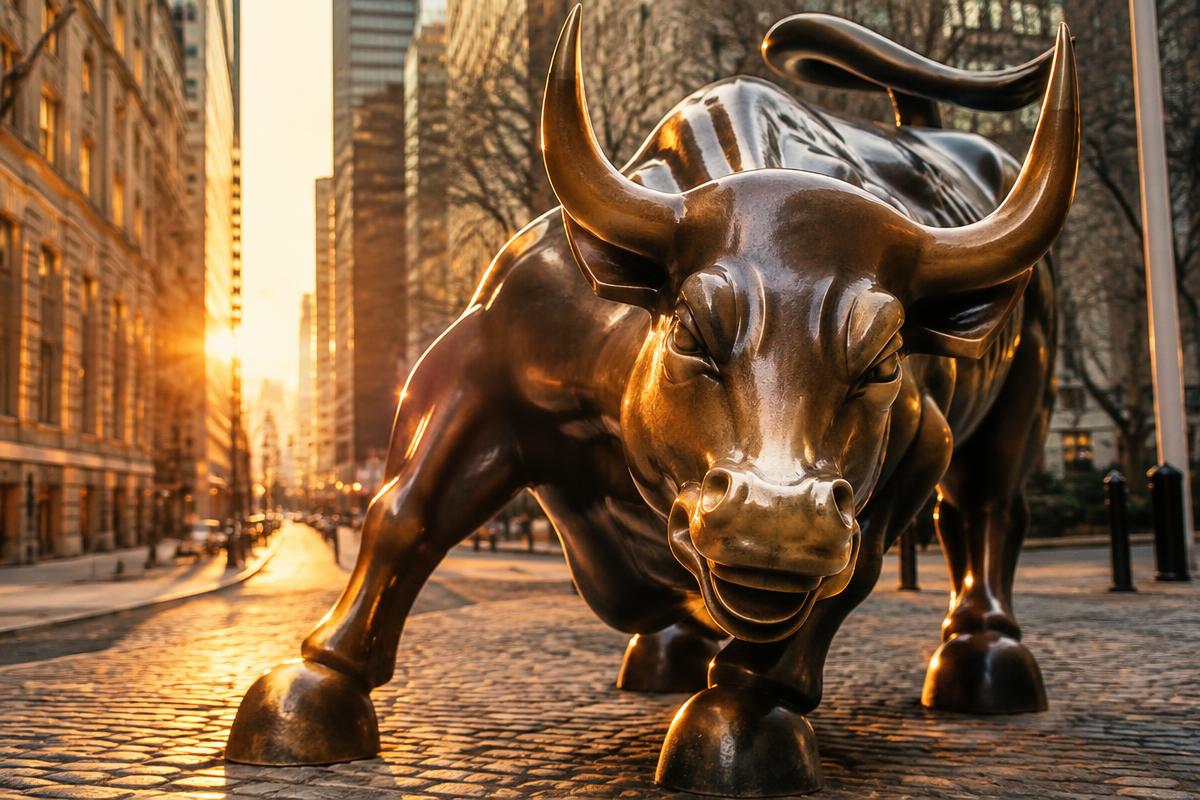
 Bull & Bear Markets
Key takeaway
A bull market is a sustained advance in stock prices. A bear market is a substantial, sustained decline. In common US market reporting, a bear market begins when a broad index closes at least 20% below a recent closing high. A rise of at least 20% from a low is often used to identify a new bull market, although analysts do not all use identical starting rules.
In this article
What bull and bear markets mean
A bull market is a sustained advance in stock prices. A bear market is a substantial, sustained decline. In common US market reporting, a bear market begins when a broad index closes at least 20% below a recent closing high. A rise of at least 20% from a low is often used to identify a new bull market, although analysts do not all use identical starting rules.
These labels describe what prices have done, not what they must do next. A bull market can contain sharp selloffs, and a bear market can contain powerful rebounds. Always ask which index, which dates, and which price measure a commentator is using. The S&P 500 tracks large US companies; the Nasdaq Composite has a different composition. One can meet a threshold before another. Your diversified portfolio can also behave differently from either benchmark, especially if it includes bonds, cash, or international stocks.
Where the animal names came from
The familiar explanation is that bulls thrust their horns upward while bears swipe downward. That image makes the terms memorable, but it is not a complete, settled account of their history. Bear terminology also has roots in early trading language about selling a bear's skin before catching the bear, a metaphor for selling something one does not yet own.
The language developed over time rather than through one universally documented naming event. Today, a bullish investor expects prices to rise, while a bearish investor expects them to fall. Those views can concern a company, an industry, or the whole market. Someone can be bullish on long-term US business growth and bearish about near-term valuations at the same time. Neither label establishes expertise. Before acting on an opinion, look for the underlying earnings assumptions, valuation, time horizon, and risks rather than treating confident animal imagery as an investment argument.
Why markets switch direction
Stock prices reflect expectations about future business cash flows and the return investors require for bearing risk. Improving earnings, lower financing costs, and greater confidence can support a bull market. Falling profits, expensive valuations, tighter credit, or a sudden shock can push prices lower. Usually several forces interact, and their importance changes during the cycle.
The economy and stock market do not move on identical schedules. Investors may sell before a recession becomes official and buy before employment or production improves. An interest-rate cut is not automatically bullish if it signals a serious deterioration in growth. Similarly, a strong jobs report can unsettle investors if it changes inflation expectations. Rather than assigning every daily move a neat explanation, separate business fundamentals from valuation changes. A company can grow earnings while its stock falls because investors are no longer willing to pay the same multiple for those earnings.
Investing during a bull market
A rising market is a good time to check whether gains have pushed your portfolio beyond its intended risk level. Suppose your target is 60% stocks and 40% bonds. A long stock advance might leave you closer to 70% stocks without any new purchases. Rebalancing restores the chosen allocation; it does not require forecasting the next market peak.
Keep contributions tied to your savings plan rather than recent headlines. Broad, low-cost funds can provide diversified exposure without requiring you to identify the next popular company. Watch overlapping holdings, since several funds can own the same large businesses. Avoid assuming that recent double-digit returns are a sustainable annual budget assumption. If money is needed soon for a home purchase or tuition, a strong market is not a reason to keep that money exposed to a large stock decline. Match the investment to the spending deadline, not the prevailing mood.
Investing during a bear market
The first task in a bear market is protecting your ability to meet expenses without forced selling. Review emergency cash, job stability, debt payments, and planned withdrawals. A long-term investor with stable income may continue regular contributions, but that is different from using rent money to buy a dip. Stocks can become cheaper and still fall substantially further.
Revisit your allocation using realistic loss scenarios. If another decline would make the plan unworkable, the original risk target may have been too aggressive. Selling solely because prices dropped can lock in losses, but refusing to change an unsuitable allocation is not discipline either. Consider taxes before realizing gains or losses in a taxable account. Tax-loss harvesting may help offset capital gains, subject to wash-sale rules and other limits. Do not let a tax benefit determine an otherwise poor investment decision or compromise diversification.
The recovery math investors overlook
Percentage losses and gains are asymmetric. An investment worth $10,000 that falls 20% becomes $8,000. Returning to $10,000 requires a 25% gain, not 20%. After a 50% decline, it takes a 100% gain to recover. These calculations assume no contributions, withdrawals, distributions, or taxes, so your actual account experience can differ.
The math explains why limiting excessive risk matters even when your horizon is long. It does not prove that you should sell whenever volatility rises. Repeatedly moving out and back in requires two successful timing decisions, and strong rebound days can occur during frightening periods. Measure performance using total return when comparing investments, because dividends matter. Also distinguish a nominal recovery from an inflation-adjusted recovery. Regaining the same dollar balance after several years does not necessarily restore the same purchasing power, especially if you withdrew money along the way.
Build rules before emotions take over
Write down your target allocation, acceptable ranges, contribution schedule, and reasons you would change the plan. Those reasons might include a new spending need, retirement, or a permanent change in income. A market label alone is usually an incomplete reason. A simple annual review or allocation-band rule can reduce the pressure to respond to every alarming headline.
Stress-test the household rather than just the portfolio. A recession may hurt wages at the same time stocks fall, so investment risk and employment risk can reinforce one another. Keep essential near-term spending separate from money intended for distant goals. When reading market commentary, look for clear index definitions and starting dates. Historical descriptions can provide perspective, but they do not set a deadline for the next recovery. The goal is a plan you can finance and follow in both kinds of market, not a perfect forecast of when one becomes the other.
Frequently asked questions
Editorial standards and sources
Globull articles are general education for US investors. Every decode is checked against public filings, company releases and exchange data, and every track record uses the price on the teaser date. Prices can be delayed and facts change, so verify important decisions with the original filing or a qualified professional.
Tags
Share this article
Written and reviewed by the Globull Research Desk
We decode newsletter teasers, check every clue against public filings and track picks over 30, 90 and 365 days. We are not paid by the publishers we cover.
Continue on Globull
- Teaser Stock LookupEvery decoded teaser with live prices and the change since the teaser date.
- Teaser DecoderPaste a newsletter pitch and see the tickers that match its clues.
- Analyst Track RecordsHow newsletter picks did after 30, 90 and 365 days against the S&P 500.
- All finance calculatorsFree calculators for returns, risk, retirement, loans and taxes. No sign-up.
Educational content for US investors, not investment advice. Prices may be delayed. Read our disclaimer.
Back to all articles